Licensed in 48 states · NAIC #10482 · A+ (Superior) carrier partners
LifeShield Family life cover
Life insurance, made human

Protect the people who call you home.

Clear cover, honest pricing and a licensed agent who actually picks up the phone. Most families get a firm offer in under 90 seconds — no medical exam required on many plans.

No obligation. No sales calls unless you ask for one.

Cover starts from $14/mo Claims paid in 4.2 days 1.2M families covered
A parent carrying two young children on his shoulders outside the family home
20-year term

$14/mo

Healthy 30-year-old · $250,000 cover

4.9 · 22,480 reviews

1.2M

Families protected

$48B

Coverage in force

4.2 days

Average claim payout

98%

Claims approved first time

Backed by
A+ Superior rated carriers State-licensed advisers Bank-grade data security Claims paid in 4.2 days 1,400 licensed agents 30% Bliss Coins offset
Three ways to protect your family

Pick the shape of cover that fits your life

Every policy below is underwritten by an A+ rated carrier and serviced by a named adviser you can call by name. Not sure which one? The estimator below points you in the right direction.

Two people making a heart shape with their hands against a sunset Most popular

Term life

Straightforward cover for a set number of years, while the mortgage, the school fees and the growing-up are all still ahead.

  • 10, 15, 20 or 30-year terms
  • Level premiums that never rise
  • No medical exam on many plans
  • Convertible to permanent cover

$14per month, from

Get term quote
An older couple sitting together on a bench looking out over the sea Lifetime cover

Whole life

Cover that never expires, with a cash value that builds quietly in the background — the closest thing to certainty in a policy.

  • Lifelong protection, guaranteed
  • Cash value that grows tax-deferred
  • Fixed premiums, fixed death benefit
  • Borrow against it if life changes

$148per month, from

Get whole quote
A mother on a sofa with her toddler and baby looking at a tablet at home Flexible

Universal life

Permanent cover where you steer the premium and the death benefit. Built for incomes that swing — freelance years, bonuses, career breaks.

  • Adjust premiums as income shifts
  • Raise the benefit when you need to
  • Indexed growth on the cash value
  • Skip-a-payment options built in

$96per month, from

Get universal quote
Compare Term life Whole life Universal life
How long it lasts10–30 years, then renews or endsYour whole lifeYour whole life
PremiumLowest — locked and levelFixed for lifeFlexible, you steer it
Cash valueNoneGuaranteed growthIndexed growth
Best forRaising children, paying off a mortgageLegacy, final costs, lifelong certaintyVariable income, changing needs
Cover amountFixedFixedAdjustable up or down
Typical starting price$14 / month$148 / month$96 / month
Coverage estimator

How much cover would actually hold the line?

Most people guess too low. Slide your numbers below and see what it takes to keep the household standing — then take it to an agent for a firm figure.

35

Premiums rise with age — locking in early is the single biggest saving.

$85,000

Before tax, everyone contributing.

10 years

10 years covers most families through school and into independence.

$220,000

Mortgage, car loans, credit cards, student debt.

2

We allow $30,000 per child toward education and care.

$60,000

Liquid savings plus any life cover you already hold.

Suggested cover

$1,010,000

Reasonsable range: $960,000 – $1,060,000

Income replaced$850,000
Debt cleared$220,000
Education & care$60,000
Savings offset−$60,000
Estimated premium
$61 per month · 20-year term · non-smoker

This is an educational estimate built on the income-replacement method. It is not a quote, an offer, or advice. Final cover and pricing depend on your health, occupation and the carrier's underwriting.

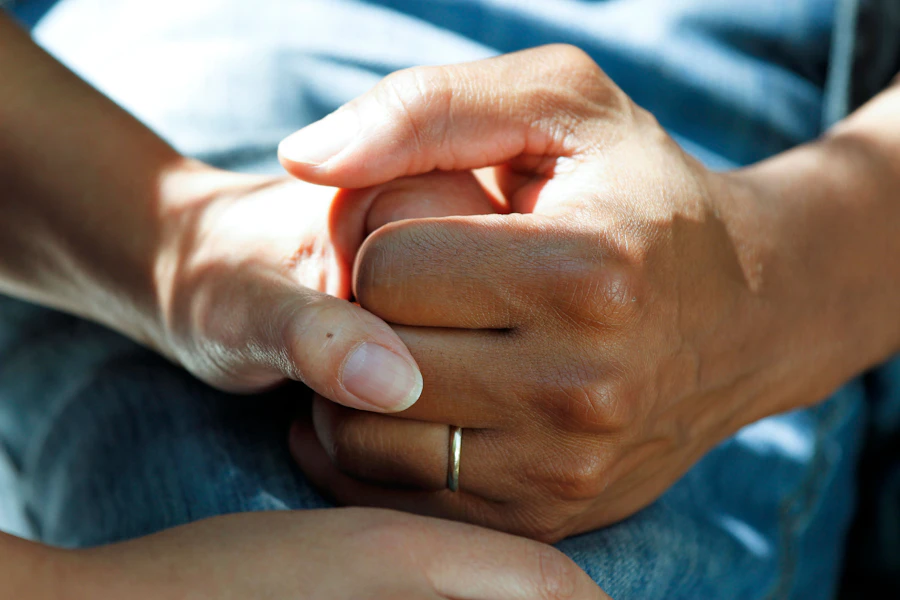
Two hands held together in warm daylight
Paid outside probate

A named beneficiary receives the benefit directly — no will, no waiting on the estate.

Beneficiaries

Decide who gets the money, and make it easy for them

The benefit goes to the people you name — not to a queue of creditors or a long court process. It takes ten minutes now and saves your family months later.

Primary & contingent

Name who you want first, then a backup in case they can't receive it. Most families split between a partner and children.

Revocable vs irrevocable

Revocable means you can change your mind any time. Irrevocable locks it in — useful for estate planning, but talk to an adviser first.

Minors need a trust

A child can't legally receive a lump sum. Name a guardian and set up a trust so the money is managed until they're grown.

Keep it current

Marriage, divorce, a new baby, a death. Every one of them is a reason to re-read your form. We'll remind you every year.

Step 01

Name your people

Full legal names, dates of birth and the share each person receives. Percentage or equal split — your call.

Step 02

Add a backup

A contingent beneficiary means a delay in one place doesn't become a delay everywhere.

Step 03

File it and forget it

We store the form with your policy, hand your family a one-page summary, and check it with you once a year.

Find an agent

A real person, licensed where you live

Search by postcode or city. Every adviser below is state-licensed, works on salary rather than commission, and will tell you when you don't need to buy.

Showing 4 of 1,400 advisers · sorted by distance from you.

Portrait of Marisol Reyes, licensed life insurance adviser

Marisol Reyes

Senior adviser · 14 yrs

San Francisco, CA

4.9 · 612 reviews

Family & termEstate
Book a call
Portrait of Daniel Whitmore, licensed life insurance adviser

Daniel Whitmore

Licensed adviser · 9 yrs

Austin, TX

4.8 · 388 reviews

TermSelf-employed
Book a call
Portrait of Kenji Nakamura, licensed life insurance adviser

Kenji Nakamura

Adviser · business cover

Seattle, WA

4.9 · 274 reviews

Key personEstate
Book a call
Portrait of Priya Anand, licensed life insurance adviser

Priya Anand

Senior adviser · 11 yrs

Chicago, IL

5.0 · 431 reviews

Whole lifeNew parents
Book a call

Nobody near you? Every adviser also runs secure video appointments — same licence, same service, from your kitchen table.

Request a virtual appointment
From families we cover

The claim is where an insurer shows who it really is

“My husband passed in March. The money landed in eleven days and nobody made me repeat the story twice. That is the whole review.”

Portrait of Helena M. Helena M. Term policy holder · Sacramento, CA

“I'm freelance, so my income is a rollercoaster. Universal life let me drop the premium to almost nothing for two slow quarters and keep the cover on.”

Portrait of Owen T. Owen T. Universal policy holder · Denver, CO

“Our adviser told us we were already covered through my work and only needed a top-up. She talked us out of the bigger policy. We stayed anyway.”

Portrait of Camille R. Camille R. Whole life policy holder · Boston, MA
Takes about 90 seconds

Get your family's number today, not after something happens.

Three questions and you'll have a firm starting price on screen. No medical exam for most healthy applicants, no pushy follow-up, and you can walk away at any point without paying a cent.

Quotes are free, unfiltered and carry no obligation to buy.

Straight answers

Questions people ask before they sign

Work cover is a good start, but it usually ends the day the job does, and the payout is often one or two years of salary. A personal policy travels with you, doesn't care who signs your payslip, and lets you choose the amount your family actually needs. Many people use work cover as a base and add personal cover on top.

For many healthy applicants under 50 and most cover amounts up to around $1 million, we can underwrite on answers alone — no needles, no clinic visit. Larger amounts or certain health histories will need a paramedical appointment, which we book and pay for.

On term cover, there's a 31-day grace period before anything lapses. On whole and universal policies, the accumulated cash value can often carry the premium for a while — and universal policies include skip-a-payment options for exactly this. Call your adviser before you miss a second payment; there is almost always a softer landing.

Yes, as often as you like — as long as you haven't made the designation irrevocable. Changes are free on every policy we arrange, take effect the moment we file them, and we'll send you a confirmation copy for your records.

Our average across the last twelve months is 4.2 days from a complete claim to funds released, and 98% of claims are approved first time. A named beneficiary receives the money directly, outside of probate, so it isn't held up by the estate. Your adviser handles the paperwork with your family personally.

No. Your details are shared with the underwriting carrier on the policy you apply for and nobody else — no lead brokers, no marketing lists. We're licensed in 48 states and bound by NAIC model privacy rules.